INTEGRATED REPORT 2019
GROUP CHIEF EXECUTIVE OFFICER’S (CEO) REVIEW
Group Chief Executive Officer:
Dr Shrey Viranna
Life Healthcare’s continued commitment to patient-centered care, efficiency and growth will unlock the significant potential we see in our business.
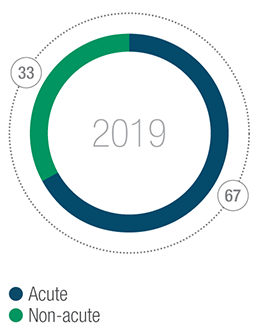
| Revenue contribution acute versus non-acute (%) | |||||||||||||||||||||||||
 |
|
I am pleased to present our 2019 integrated report as I near the end of my second year as Group CEO. Despite a challenging macro-economic backdrop, Life Healthcare delivered a healthy overall performance in 2019 as supported by the numbers presented. In addition, we have strengthened our balance sheet during 2019, through a combination of continued focus on cost efficiency, capital discipline, and utilising the proceeds from the disposal of our associate investment in India to reduce debt levels. Furthermore, our business is starting to see the benefits from our key efficiency and cost optimisation initiatives.
Our macro-environment
Globally, the healthcare landscape is evolving rapidly due to macro-economic, political and regulatory and technological factors that influence the Group's performance in southern Africa and internationally. We are acutely aware of the requirements to anticipate and respond to these dynamics. As a management team we pride ourselves in the speed at which we adapt our plans and strategies to respond to these factors.
Although the key markets we operate in were destabilised by a number of factors, including uncertainties related to poor economic growth in South Africa, Brexit, as well as trade and political tensions between the United States and China, the key factor impacting our business remains the poor economic growth in South Africa. This negatively affects the healthcare sector as the number of privately insured people remained static due to low employment growth and some consumers opting for lower cost medical aid plans. In an environment like this we, however, still see pockets of growth and we are actively focusing to adapt our operating model in the acute hospitals to remain relevant in a low-growth environment.
Our 2019 operating and financial performance
Southern Africa
We continue to focus on improving our clinical quality, clinical outcomes and patient experience. This focus has resulted in adverse patient safety events that are declining and, overall, our patient experience is consistently in line with targets. Our southern Africa business in 2019 became the first hospital group in South Africa to publish quality scores on a per hospital basis, which was disclosed from October 2018.
In spite of a quiet Q1, the southern Africa operations ended with strong revenue growth for the financial year and 0.8% PPD growth. The management team in southern Africa was able to correct the slow start to the financial year through renewed focus on cost management and benefitting from doctor recruitment in 2018 and 2019 to deliver a healthy performance in the South African market. The overall weighted occupancy for the year remained in line with the prior year at 69.7%, with the addition of 17 acute brownfield expansion beds and 80 mental health beds. Complementary services continued to show good growth with revenue increasing by 9.2%, benefitting from the opening of the new mental health unit at Life Brackenview and good growth in renal dialysis. The southern Africa healthcare services segment performed well with revenue growing by 12.2%, largely due to new contracts gained by Life Employee Health Solutions. The normalised EBITDA margin continues to be impacted by the dynamic in southern Africa of below inflationary increases in pricing while costs increased by above inflation. In this environment, the Group has done well with the margin decreasing by 1.4% only excluding the factors listed below. The margin decreased to 23.8% from 24.9% in 2018 and was primarily impacted by the lower PPD activity in the first four months of the 2019 financial year, which affected operational leverage in H1 FY2019, the costs of additional human resource capacity at corporate level to support growth initiatives and the initial cost of efficiency programmes which are expected to deliver future efficiency gains. Normalised EBITDA excluding corporate costs increased by 6.4%.
International
Likewise to southern Africa, our international business continued to focus on providing the highest levels of patient care and technical excellence. We continue differentiating offerings through quality service delivery and standards, building long-term stakeholder relationships. Our newly developed Group clinical quality and governance framework provided the foundation for the initiation of a number of clinical governance and quality integration projects across the various country teams.
Alliance Medical's revenue grew by 13.4% to R5.6 billion. The main factors driving revenue growth were the PET-CT scan volumes increasing 15.9% from the prior year, the acquisition of the Italian clinics during H2 FY2018, an acquisition of three scanning facilities (ESC) in the United Kingdom in the current period, and a good performance in Italy and Ireland. Normalised EBITDA increased by 3.9% to R1.3 billion (2018: R1.2 billion). The normalised EBITDA margin declined to 22.4% (2018: 24.5%), being primarily impacted by short-term operational challenges within our radiopharmacy production units in the UK which resulted in increased costs as we undertake an 18-month planned refurbishment programme. Excluding this impact, the margin was 23.6%.
Healthcare services' (Scanmed) revenue for the year increased by 7.1% to R1.4 billion while normalised EBITDA increased to R97 million (2018: R85 million) resulting in the normalised EBITDA margin increasing to 7.2% (2018: 6.7%). Healthcare services' performance was impacted by reduced over-quota referrals during FY2019, increased competition in orthopaedics, costs relating to IT automation projects, and costs associated with bolstering the strength of our management team.
Growth initiatives
Our strategy centres on operational excellence first but also to grow the business. We have identified a number of new growth segments we are exploring.
In southern Africa, we are making good progress in developing new growth segments. We are developing the imaging opportunity, investing in data analytics and broadening our business lines across the healthcare continuum.
Alliance Medical is the leading independent provider of medical imaging services in Europe, operating across 13 countries. In South Africa, we have an opportunity to offer high-quality, affordable diagnostic imaging services by integrating these services into our infrastructure, leveraging Alliance Medical's expertise and improving scale, standardisation and efficiency. We intend to make a substantial short to medium-term deep investment into providing imaging services in southern Africa to both government and private healthcare organisations as a key pillar of future growth.
As the employed uninsured population is not adequately served by traditional primary healthcare models, we want to improve healthcare access and affordability by offering convenient, quality outpatient care, delivered via cutting-edge technology and scaled through partnerships. During 2019, Life Healthcare opened its first outpatient clinic called MyLife Healthcare Centre. We proved our ability to operate a low cost, efficient, high-quality service, with consistently high patient experience scores. This pilot site has enabled us to evolve our operating model, and we are now working to expand and scale this offering with the launch of a partnership with a large retailer to test the outpatient model in some of their stores.
Internationally, we are growing our radiology product development business within Alliance Medical through our investment in LMI, which outperformed and contributed revenue of R268 million (2018: R66 million). LMI will focus on driving sales of Neuraceq, a radioactive tracer used to identify Amyloid plaques in the brain in order to diagnose Alzheimer's disease. A pipeline of products is progressing well through various stages of development, with a phase 2 study for Tau tracer commenced in the year. We have a positive outlook for the LMI business following the Biogen announcement of the success with a disease modifying drug and the filing with FDA for approval.
Max Healthcare sale
On 21 June 2019, the Group concluded the disposal of its Max Healthcare 49.7% equity shareholding for R4.3 billion. The net proceeds of approximately R3.8 billion was utilised to reduce debt levels.
Outlook
Even though we anticipate continued tough operating conditions, largely due to slow economic growth and increased network arrangements that place pressure on tariffs in South Africa and uncertainty in the regulatory environment in Europe due to a potential Brexit, the Group foresees pockets of growth.
In southern Africa, we expect flat acute PPD growth depending on network arrangements and an upward trend in complementary services. The Group will continue to take a cautious approach with regard to bed expansion and is targeting adding only 50 beds in 2020. We maintain our focus on operational excellence, improving clinical quality and driving new growth initiatives, and expect the efficiency programmes we implemented in 2019 to assist in stabilising EBITDA margins. As a Group, our contribution to building SA's healthcare needs in training and development of nurses and other healthcare professionals will continue to grow.
In the UK, we will complete the roll-out of the PET wave 2 contract and resolve radioisotope production issues. We expect an additional cyclotron to be operational in H2 2020 that is expected to resolve the current production issues we face. Until this cyclotron is operational, the business will focus on careful management of radioisotope production in an environment of an expected increase in PET-CT volumes. In the other international imaging markets we operate, we will continue to focus on operational excellence and to pursue select bolt-on acquisitions to grow these markets. In Poland, we have appointed an adviser to explore a potential disposal of the business.
We will continue to progress the opportunity in the southern Africa imaging market, implement the outpatient model, deliver on our LMI strategy, continue with global integration, and deepen initial analytics-use cases targeting operational efficiency improvements.
Appreciation
I would like to thank our board and executive management teams for their dedication during the year. To our employees and the healthcare professionals with whom we work, thank you for your passion and fervour every day. Your commitment to providing quality care to our patients is key to the success of our business.
I believe our business is well positioned to continue providing high-quality care to our current and future patients, and to continue creating sustainable value for our stakeholders. I look forward to seeing Life Healthcare deliver on our ambitions for the year ahead.
Dr Shrey Viranna
Group CEO