INTEGRATED REPORT 2019
Independent auditor's report
To the Shareholders of Life Healthcare Group Holdings Limited
Report on the audit of the consolidated and separate financial statements
Our opinion
In our opinion, the consolidated and separate financial statements present fairly, in all material respects, the consolidated and separate financial position of Life Healthcare Group Holdings Limited (the Company) and its subsidiaries (together the Group) as at 30 September 2019, and its consolidated and separate financial performance and its consolidated and separate cash flows for the year then ended in accordance with International Financial Reporting Standards and the requirements of the Companies Act of South Africa.
What we have audited
Life Healthcare Group Holdings Limited's consolidated and separate financial statements set out comprise:
- the consolidated statement of financial position and the company statement of financial position as at 30 September 2019;
- the consolidated statement of profit or loss and other comprehensive income and the company statement of profit or loss and other comprehensive income for the year then ended;
- the consolidated statement of changes in equity and the company statement of changes in equity for the year then ended;
- the consolidated statement of cash flows and the company statement of cash flows for the year then ended;
- the notes to the consolidated annual financial statements;
- the notes to the company annual financial statements, which include a summary of significant accounting policies;
- Annexure A: Significant accounting policies;
- Annexure B: Simplified group structure; and
- Annexure C: Associate undertakings.
Basis for opinion
We conducted our audit in accordance with International Standards on Auditing (ISAs). Our responsibilities under those standards are further described in the Auditor's responsibilities for the audit of the consolidated and separate financial statements section of our report.
We believe that the audit evidence we have obtained is sufficient and appropriate to provide a basis for our opinion.
Independence
We are independent of the Group in accordance with sections 290 and 291 of the Independent Regulatory Board for Auditors' Code of Professional Conduct for Registered Auditors (Revised January 2018), parts 1 and 3 of the Independent Regulatory Board for Auditors' Code of Professional Conduct for Registered Auditors (Revised November 2018) (together the IRBA Codes) and other independence requirements applicable to performing audits of financial statements in South Africa. We have fulfilled our other ethical responsibilities, as applicable, in accordance with the IRBA Codes and in accordance with other ethical requirements applicable to performing audits in South Africa. The IRBA Codes are consistent with the corresponding sections of the International Ethics Standards Board for Accountants' Code of Ethics for Professional Accountants and the International Ethics Standards Board for Accountants' International Code of Ethics for Professional Accountants (including International Independence Standards) respectively.
Our audit approach
Overview
 |
Overall Group materiality | |
|
||
| Group audit scope | ||
|
||
| Key audit matters | ||
|
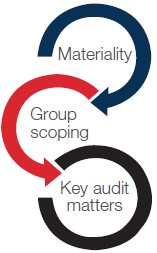
As part of designing our audit, we determined materiality and assessed the risks of material misstatement in the consolidated and separate financial statements. In particular, we considered where the directors made subjective judgements; for example, in respect of significant accounting estimates that involved making assumptions and considering future events that are inherently uncertain. As in all of our audits, we also addressed the risk of management override of internal controls, including among other matters, consideration of whether there was evidence of bias that represented a risk of material misstatement due to fraud.
Materiality
The scope of our audit was influenced by our application of materiality. An audit is designed to obtain reasonable assurance whether the financial statements are free from material misstatement. Misstatements may arise due to fraud or error. They are considered material if individually or in aggregate, they could reasonably be expected to influence the economic decisions of users taken on the basis of the consolidated financial statements.
Based on our professional judgement, we determined certain quantitative thresholds for materiality, including the overall Group materiality for the consolidated financial statements as a whole as set out in the table below. These, together with qualitative considerations, helped us to determine the scope of our audit and the nature, timing and extent of our audit procedures and to evaluate the effect of misstatements, both individually and in aggregate on the financial statements as a whole.
|
Overall group materiality |
R123 million |
|
|
How we determined it |
5% of adjusted consolidated profit before tax (adjusted for once off items including impairment charges on the Poland operations R125 million, profit on disposal of investment in Max India joint venture R1 501 million and transaction costs relating to the disposal of investment in Max India joint venture R118 million). |
|
|
Rationale for the materiality benchmark applied |
We chose profit before tax, adjusted for non-recurring items, as the benchmark because, in our view, it is the benchmark against which the performance of the Group is most commonly measured by users, and is a generally accepted benchmark. We chose 5% which is consistent with quantitative materiality thresholds used for profit-oriented companies in this sector. |
|
How we tailored our Group audit scope
We tailored the scope of our audit in order to perform sufficient work to enable us to provide an opinion on the consolidated financial statements as a whole, taking into account the structure of the Group, the accounting processes and controls, and the industry in which the Group operates.
In-scope business units were identified based on scoping benchmarks such as the business unit's contribution to key financial statement line items (consolidated profit before tax, consolidated revenue and consolidated total assets) and risks associated with the business unit.
In establishing the overall approach to the Group audit, we determined the type of work that needed to be performed by us, as the Group engagement team, or component auditors from other PwC network firms or other networks operating under our instruction. Where the work was performed by component auditors, we determined the level of involvement we needed to have in the audit work at those components to be able to conclude whether sufficient appropriate audit evidence had been obtained as a basis for our opinion on the consolidated financial statements as a whole.
The audits undertaken for Group reporting purposes are in respect of the key reporting business units of the Group, equating to full scope audit procedures being performed at 25 business units. We performed audit procedures on specific financial statement line items at a further 3 business units.
Key audit matters
Key audit matters are those matters that, in our professional judgment, were of most significance in our audit of the consolidated and separate financial statements of the current period. These matters were addressed in the context of our audit of the consolidated and separate financial statements as a whole, and in forming our opinion thereon, and we do not provide a separate opinion on these matters.
The following key audit matters relate to the consolidated financial statements. We have determined that there are no key audit matters in respect of the separate financial statements to communicate in our report.
| Key audit matter | How our audit addressed the key audit matter | |
|
Impairment consideration of goodwill and non-financial assets Refer to note 1.2 (Critical judgements, accounting estimates and assumptions – non-financial assets), note 10 (Property, plant and equipment) and note 11 (Intangible assets) to the consolidated financial statements. At 30 September 2019 the Group's consolidated statement of financial position included property, plant and equipment amounting to R12 929 million and goodwill amounting to R13 141 million relating to both its southern Africa and international operations. An impairment assessment of non-financial assets is required to be performed by management when there is an indication that these assets may be impaired. Assets that are not amortised, such as goodwill and indefinite life intangible assets are required to be assessed for impairment annually even if there is no impairment indicator. Alliance Medical Group (UK): Management performed an impairment assessment for the Alliance Medical Group cash-generating unit ("CGU"), using the value in use model to identify if the recoverable amount is less than the carrying amount. Management applied judgement in the determination of key assumptions and future market conditions, particularly in relation to:
Future cash flows are estimated based on financial budgets covering a five-year period. Based on the results of the impairment assessment, management did not recognise an impairment in respect of the Alliance Medical Group at 30 September 2019. Poland operations: Management performed impairment assessments for all CGUs within Poland with allocated goodwill using the value in use model based on five-year cash flow forecasts with a terminal value. Management applied judgement in the determination of key assumptions and future market conditions, particularly in relation to:
|
Through our discussions with management and inspection of underlying calculations, we gained an understanding of the methodology and calculations used by management for impairment assessment purposes, which consisted of discounted cash flow calculations. Impairment consideration of goodwill We evaluated management's impairment assessments, considering the key assumptions and estimates by performing the following procedures:
Based on the results of our independently performed calculations and sensitivity analysis, management's assessment was found to be within an acceptable range of our independent assessment. |
|
|
Poor current and previous period results and regulatory changes are impairment indicators which may impact the assessment of the recoverable amounts of non-financial assets. Management performed a specific impairment assessment in relation to a CGU, which is an individual hospital, where these impairment indicators were identified. As the value in use calculation for the one hospital indicated an impairment, management engaged external valuators in determining the higher of value in use and fair value less cost of disposal in determining the recoverable amount of this hospital. The fair value method was used, and the valuation was based on market values as independently determined by an external valuer using the direct capitalisation valuation methodology. Impairments of R103 million and R22 million were recognised in relation to property, plant and equipment and computer software respectively, at 30 September 2019. Southern Africa operations: CGUs within the southern Africa operations are defined as individual hospitals and healthcare service operating units. Goodwill is allocated to these operations based on expected benefit arising from synergies due to the business combinations. At 30 September 2019, goodwill in relation to the southern Africa operations amounted to R1.3 billion. Management performed annual impairment assessments on the cash-generating units to which goodwill has been allocated based on value in use calculations. Management applied judgement in the determination of key assumptions and future market conditions, particularly in relation to:
Future cash flows are estimated based on financial budgets covering a five-year period. Based on the results of the impairment assessments, management did not recognise an impairment in respect of the southern Africa operations at 30 September 2019. The impairment consideration of goodwill and non-financial assets was considered to be a matter of most significance to the current year audit for the following reasons:
|
Impairment of non-financial assets for Poland operations We evaluated management's impairment assessment, by performing the following procedures:
|
|
|
Adoption of new accounting standard – IFRS 9 Financial Instruments Refer to note 1.2 (Critical judgements, accounting estimates and assumptions – Financial instruments) and note 16 (Trade and other receivables) to the consolidated financial statements. In the current financial year, the Group has adopted IFRS 9 'Financial Instruments' (IFRS 9). This resulted in the Group revising its financial asset impairment methodology from an incurred loss model to an expected credit loss (ECL) model. In calculating the provision on transition to IFRS 9 for trade receivables, the Group applied the simplified approach to measure the ECLs, which uses a lifetime expected loss allowance. Management used in-house and external experts to perform IFRS 9 impairment assessments on the trade receivables. The initial application of IFRS 9 resulted in a decrease in the impairment provision and subsequent increase in trade receivables as disclosed in note 16 to the financial statements. The difference on initial application was recognised in opening retained earnings. This was considered to be a matter of most significance to the current year audit for the following reasons:
|
We assessed the competence, capabilities and objectivity of management's external experts by verifying their qualifications. We found management's external experts had the necessary qualifications and there was no evidence to suggest that their objectivity was compromised. We also determined whether there are any matters that might have affected the independent valuer's objectivity or may have imposed scope limitations upon the work performed by the independent valuer. With the assistance of our actuarial experts, we:
|
|
Other information
The directors are responsible for the other information. The other information comprises the information included in the document titled "Life Healthcare Group Annual Financial Statements 2019", which includes the Directors' Report, the Report of the audit committee and the Statement of Group Company Secretary as required by the Companies Act of South Africa, which we obtained prior to the date of this auditor's report, and the document titled "Life Healthcare Group Integrated Report 2019", which is expected to be made available to us after that date. The other information does not include the consolidated or the separate financial statements and our auditor's report thereon.
Our opinion on the consolidated and separate financial statements does not cover the other information and we do not and will not express an audit opinion or any form of assurance conclusion thereon.
In connection with our audit of the consolidated and separate financial statements, our responsibility is to read the other information identified above and, in doing so, consider whether the other information is materially inconsistent with the consolidated and separate financial statements or our knowledge obtained in the audit, or otherwise appears to be materially misstated.
If, based on the work we have performed on the other information that we obtained prior to the date of this auditor's report, we conclude that there is a material misstatement of this other information, we are required to report that fact. We have nothing to report in this regard.
Responsibilities of the directors for the consolidated and separate financial statements
The directors are responsible for the preparation and fair presentation of the consolidated and separate financial statements in accordance with International Financial Reporting Standards and the requirements of the Companies Act of South Africa, and for such internal control as the directors determine is necessary to enable the preparation of consolidated and separate financial statements that are free from material misstatement, whether due to fraud or error.
In preparing the consolidated and separate financial statements, the directors are responsible for assessing the Group and the Company's ability to continue as a going concern, disclosing, as applicable, matters related to going concern and using the going concern basis of accounting unless the directors either intend to liquidate the Group and/or the Company or to cease operations, or have no realistic alternative but to do so.
Auditor's responsibilities for the audit of the consolidated and separate financial statements
Our objectives are to obtain reasonable assurance about whether the consolidated and separate financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue an auditor's report that includes our opinion. Reasonable assurance is a high level of assurance, but is not a guarantee that an audit conducted in accordance with ISAs will always detect a material misstatement when it exists. Misstatements can arise from fraud or error and are considered material if, individually or in the aggregate, they could reasonably be expected to influence the economic decisions of users taken on the basis of these consolidated and separate financial statements.
As part of an audit in accordance with ISAs, we exercise professional judgement and maintain professional scepticism throughout the audit. We also:
- Identify and assess the risks of material misstatement of the consolidated and separate financial statements, whether due to fraud or error, design and perform audit procedures responsive to those risks, and obtain audit evidence that is sufficient and appropriate to provide a basis for our opinion. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from error, as fraud may involve collusion, forgery, intentional omissions, misrepresentations, or the override of internal control.
- Obtain an understanding of internal control relevant to the audit in order to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the Group's and the Company's internal control.
- Evaluate the appropriateness of accounting policies used and the reasonableness of accounting estimates and related disclosures made by the directors.
- Conclude on the appropriateness of the directors' use of the going concern basis of accounting and, based on the audit evidence obtained, whether a material uncertainty exists related to events or conditions that may cast significant doubt on the Group's and the Company's ability to continue as a going concern. If we conclude that a material uncertainty exists, we are required to draw attention in our auditor's report to the related disclosures in the consolidated and separate financial statements or, if such disclosures are inadequate, to modify our opinion. Our conclusions are based on the audit evidence obtained up to the date of our auditor's report. However, future events or conditions may cause the Group and/or Company to cease to continue as a going concern.
- Evaluate the overall presentation, structure and content of the consolidated and separate financial statements, including the disclosures, and whether the consolidated and separate financial statements represent the underlying transactions and events in a manner that achieves fair presentation.
- Obtain sufficient appropriate audit evidence regarding the financial information of the entities or business activities within the group to express an opinion on the consolidated financial statements. We are responsible for the direction, supervision and performance of the group audit. We remain solely responsible for our audit opinion.
We communicate with the directors regarding, among other matters, the planned scope and timing of the audit and significant audit findings, including any significant deficiencies in internal control that we identify during our audit.
We also provide the directors with a statement that we have complied with relevant ethical requirements regarding independence, and to communicate with them all relationships and other matters that may reasonably be thought to bear on our independence, and where applicable, related safeguards.
From the matters communicated with the directors, we determine those matters that were of most significance in the audit of the consolidated and separate financial statements of the current period and are therefore the key audit matters. We describe these matters in our auditor's report unless law or regulation precludes public disclosure about the matter or when, in extremely rare circumstances, we determine that a matter should not be communicated in our report because the adverse consequences of doing so would reasonably be expected to outweigh the public interest benefits of such communication.
Report on other legal and regulatory requirements
In terms of the IRBA Rule published in Government Gazette Number 39475 dated 4 December 2015, we report that PricewaterhouseCoopers Inc. has been the auditor of Life Healthcare Group Holdings Limited for 21 years.
PricewaterhouseCoopers Inc.
Director: AJ Rossouw
Registered Auditor
Waterfall City
21 November 2019